Money management works best when it follows the rhythm of the calendar instead of depending on willpower or occasional bursts of motivation. Many households are caught off guard by costs that repeat every year, such as summer trips, autumn school supplies, winter heating bills, and spring home upkeep. A budget that treats every month as identical makes those costs feel like emergencies.
A seasonal calendar solves that problem by giving each quarter a short set of money tasks. You do not need complicated jargon or daily spreadsheets to feel in control of household cash flow. A single unhurried hour at the start of each season, spent reviewing transfers and planning ahead, keeps the whole budget steady.
Winter Cash Flow Resets and Subscription Checks
January and February follow the spending of the holiday period, which makes them a natural time for a reset. Review bank and card statements from the last few months to find recurring subscriptions, unused memberships, and small automatic charges that have quietly grown. Cancelling services you no longer use and sending those dollars to an automatic savings transfer builds momentum without feeling restrictive.
Readers may also want to visit Ilearnuk.com. Dividing savings into labeled sub-accounts, such as vehicle repairs, medical deductibles, and gift money, stops predictable costs from disturbing everyday checking balances. Winter is also a good moment to check tax withholding on paychecks and confirm that automatic utility payments match current seasonal bills.
Spring Records and Home Project Limits
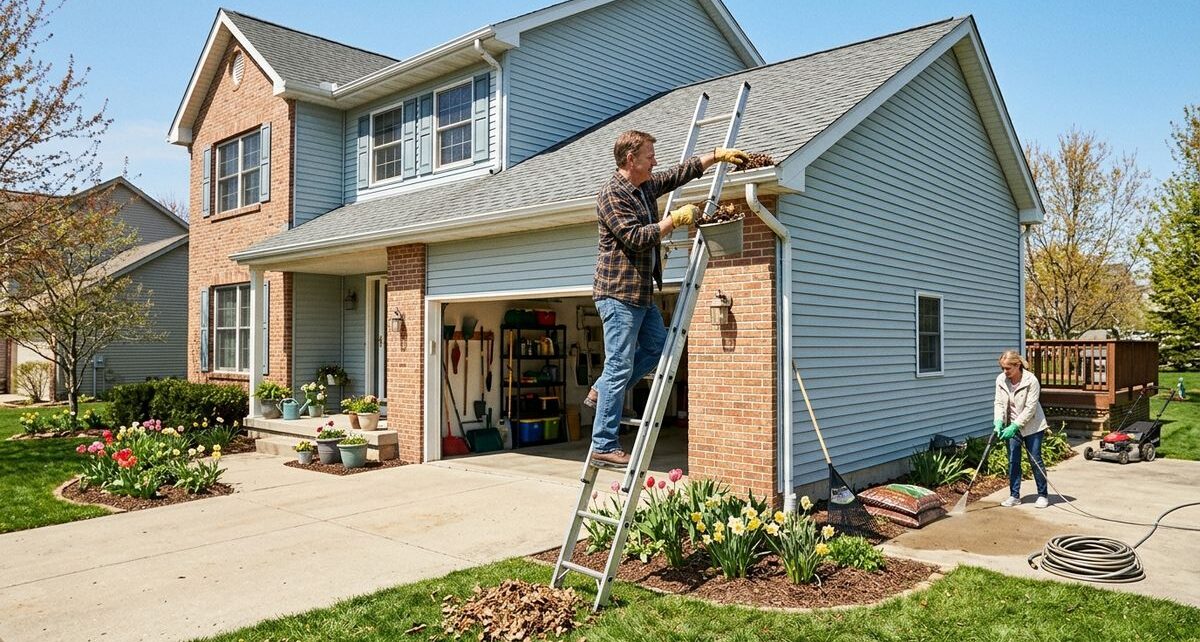
As spring arrives, attention naturally turns to gathering tax documents, organizing household folders, and planning outdoor projects. Create one labeled binder or encrypted digital folder for income forms, charitable receipts, and appliance warranties, which saves hours of searching later. Setting a firm spending limit before a trip to the garden center or hardware store keeps sunny-day impulse purchases from straining the monthly plan.
You can also visit Raku Raku School for more reading. Reviewing auto, renters, and homeowners policies each spring confirms that coverage still matches the household’s current needs. Spring is also a sensible time to look at winter heating totals and set aside a modest buffer for summer cooling costs.
Summer Spending and Mid-Year Checks
July and August bring road trips, day camps, and weekend outings that can quickly inflate dining and entertainment spending if they are not planned. Creating a summer fun fund early in the year lets a family enjoy outings without carrying balances into autumn. Keeping that fund separate makes it easy to see how much is left.
For a related read on this site, see A Step-by-Step Routine for Resolving Everyday Customer Service. A short check-in during the middle of the year shows whether annual savings targets are on track or need a gentle adjustment before the second half begins.
Autumn Enrollment and Holiday Budgets
September and October mark workplace benefit enrollment windows and the right moment to set holiday gift budgets before promotions begin. Listing gift recipients, choosing a realistic limit for each person, and shopping gradually through the autumn months prevents financial stress when December arrives. Choosing benefits carefully during open enrollment also keeps the coming year’s costs predictable.
A seasonal money calendar works best when each quarter ends with a short written note. Record what was spent, what was saved, and which bill or habit surprised you. Those notes make next year’s planning far easier than trying to remember the details from memory.
Emergency savings deserve a regular place on the calendar. Aim to add a small, fixed amount each month, and increase it when a bonus or tax refund arrives. A cushion that grows steadily protects the household from a broken appliance or an unexpected medical bill without forcing a loan.
Finally, build in a little room for enjoyment. A budget that allows for birthdays, friends, and small pleasures is far easier to maintain than one that leaves no space at all. Planning those pleasures in advance means they feel like part of the plan rather than an exception to it.
Closing Thoughts
A four-season money calendar turns scattered financial chores into a calm, repeatable routine. Reviewing the full year each December celebrates progress and sets a realistic footing for the months ahead.